 602-743-5100
 Jennifer@Srock.net


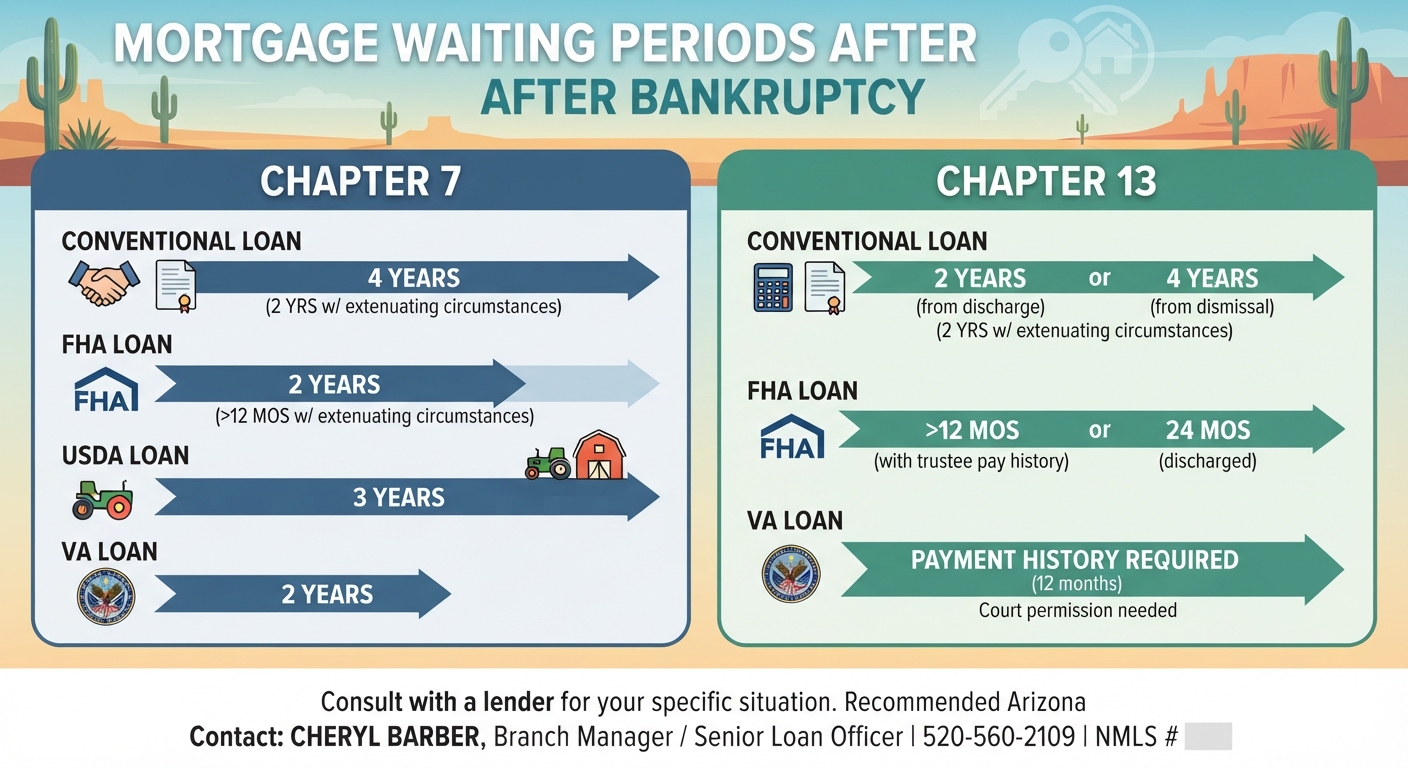
A quick guide to mortgage waiting periods after Chapter 7 and Chapter 13 bankruptcy for Conventional, FHA, VA, and USDA loans.
By Jennifer Srock
How long must buyers wait before obtaining mortgage financing?
Keep in mind you will always need to examine your specific situation with your mortgage lender. The following is general information. I always recommend Arizona buyers contact a Loan Officer for a free consultation on qualifying for a mortgage loan. Ask me for some recommendations to shop.
So, here are the facts:
Chapter 7 Bankruptcy:
On a conventional loan (applies to both chapters 7 & 11) – 4 years from discharge or dismissal date. Due to extenuating circumstances, you may eligible for reduced seasoning time so long as you have re-established credit for 2 years and provide a letter of explanation and documentation evidencing the incident was not due to a financial mismanagement. Acceptable situations include:
- Death of primary wage earner
- Long-term illness or disability not covered by insurance
- Prolonged loss of employment for reasons beyond the borrower’s control (such as closing mergers)
On an FHA loan – 2 years from discharge date or may be eligible for the reduced seasoning time due to extenuating circumstances. Borrower would need to have re-established credit for 2 years and provide a letter of explanation and provide documentation evidencing the incident was not due to financial mismanagement. >12 months & < 24 months. Same Acceptable situations included for conventional loan above.
On a USDA Rural loan – 3 years from discharge or dismissal date.
On a VA loan – 2 years from discharge or dismissal date.
Chapter 13 Bankruptcy:
On a conventional loan – 2 years from discharge date or 4 years from dismissal date. You may get an exception for 2 years from either discharge or dismissal date with extenuating circumstances such as
- Death of primary wage earner
- Long-term illness or disability not covered by insurance
- Prolonged loss of employment for reasons beyond the borrower’s control (such as closing mergers)
On an FHA loan – >12 mos. & <24 mos. discharge with pay history from the trustee. 24 mos. discharged is ok. 1 year of the payout must have elapsed and payments made on time. Borrower must receive permission from the courts to enter into a mortgage. High balance is 7 years.
On a USDA Rural loan – >12 mos. & <24 mos. discharge with pay history from the trustee. 24 mos. discharged is ok. 1 year of the payout must have elapsed and payments made on time. Borrower must receive permission from the courts to enter into a mortgage.
On a VA loan – Documentation of the debt restructure is required along with acceptable 12 month payment history of the debts included in the bankruptcy. Must provide documentation of the court’s permission to proceed. There may be additional requirements per the Automated Underwriting System.
Leave a Reply